Technology · Investing · Strategy

Featured

Featured Big Thought

Nvidia Is Becoming the AI Nation-State

Nvidia Is Becoming the AI Nation-State

There is plenty of talk about circular financing in AI, especially around Nvidia. The concern is legitimate. But the phrase carries historical baggage. In its worst forms, circular financing manufactured the appearance of demand: a vendor financed its own customers and then presented those purchases as evidence of genuine, independent market demand. That can become a house of cards very quickly.

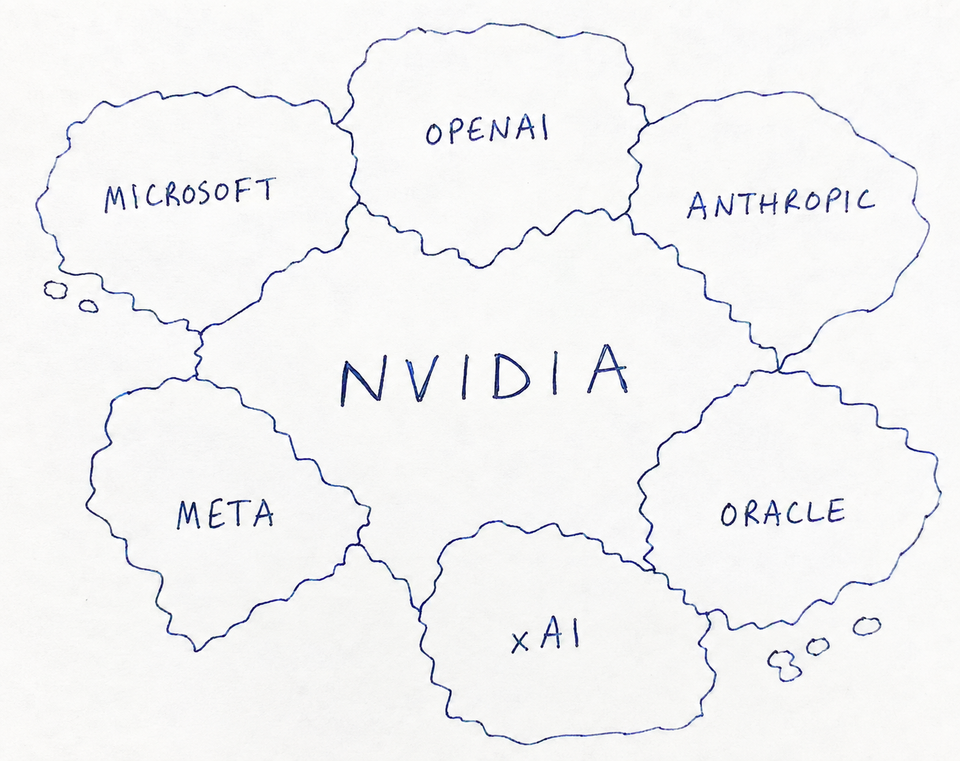
Recent reports that Nvidia has supported financing for major AI infrastructure projects have reignited those concerns. But Nvidia may be doing something fundamentally different. It is increasingly behaving less like a semiconductor company and more like a nation state investing in a strategically important industry.

Nation states subsidize industries because creating scale can ultimately benefit the entire country. China's support for its EV industry helped domestic manufacturers reach the scale needed to compete globally, generating benefits through exports, employment, technological leadership and supply-chain control. Nvidia may be making a similar calculation. If helping customers build AI infrastructure today produces a much larger AI economy tomorrow, the payoff is not merely today's "circular" GPU sale. It is the next decade of demand for Nvidia's computing platform.

The obvious question is why conventional finance is not providing all the necessary capital. Nvidia has several advantages over ordinary lenders. AI projects are extraordinarily large and create concentration, duration and technology risks that conventional lenders may struggle to understand, let alone absorb. Nvidia has both substantial financial capacity and a strategic reason to accept those risks. Traditional lenders seek repayment. Nvidia seeks ecosystem expansion. Those are fundamentally different objectives. It also sees demand across the AI ecosystem rather than through the financial statements of a single borrower, and likely understands deployment progress, technical risk and the residual value of its own hardware far better than a bank. These asymmetric informational advantages may allow it to assess risk more accurately.

But perhaps the most important difference is that Nvidia captures ecosystem externalities that private capital largely cannot. Every successful AI deployment expands the CUDA developer base, creates new applications, attracts more developers and ultimately increases demand for future AI infrastructure. A bank finances a single project and earns interest. Nvidia helps finance an ecosystem and earns a larger future market.

This is where the nation-state analogy becomes most compelling. Governments often subsidize strategically important industries because the long-term benefits spill far beyond the companies receiving the investment. Private investors cannot capture those broader returns, so markets may rationally underinvest. Nvidia may occupy a similarly unusual position. It captures enough of those ecosystem-wide benefits that investing in AI infrastructure could be economically rational even when conventional financiers would hesitate.

The strongest counterargument returns to the opening question of genuine market demand. Nvidia may understand medium-term demand for GPUs better than anyone else, but that does not necessarily mean it can predict whether businesses and consumers will ultimately derive enough value from AI to justify today's extraordinary investment. If AI applications fail to generate the expected economic value, the flywheel breaks. Nvidia may then simply have accelerated future purchases into the present rather than helping create a self-sustaining market. The nation-state strategy works only if the industry being subsidized can eventually thrive on its own.

I think it will. Where others see problematic circular financing, I see smart investment in the next industrial revolution. That's the bet I'm making.

Disclosure: I am long Nvidia.
Featured Big Thought

Meta Needs AI but maybe not AGI

Meta Needs AI but maybe not AGI

Meta Needs AI but maybe not AGI

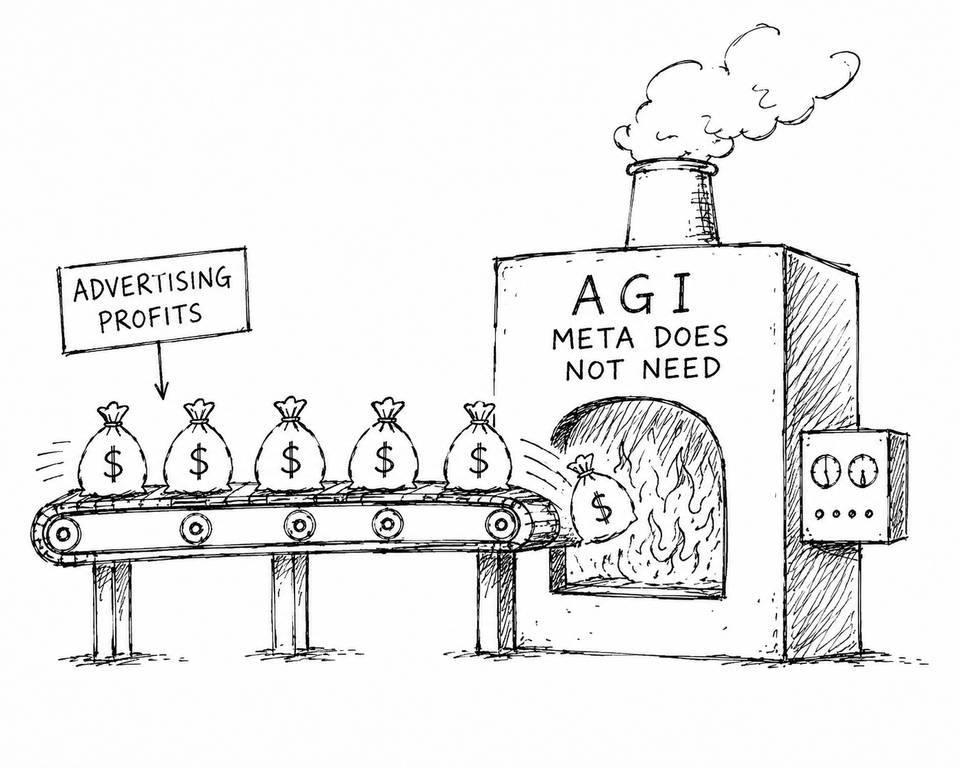
Why is Meta trying to compete at the AI frontier and pursue “personal superintelligence”? It is a question I return to every earnings call, because Zuckerberg has yet to offer an economically compelling answer.

Meta unquestionably needs AI. Machine learning drives ad targeting, recommendations and engagement, and the results have been fabulous: users spend more time on Reels, advertisers receive better conversions, and Meta’s core grab-eyeballs-and-sell-ads flywheel is kicking a lot of ass. Indeed, European regulators now object that their platforms are becoming too addictive—a ringing implicit endorsement if ever I saw one. So far so great.

Building much of that technology internally absolutely makes strategic sense. Meta does not want its core products dependent on frontier labs—or, worst case, Google, its largest advertising rival—charging it high rents for essential models.

But none of that explains why Meta needs to own the frontier.

Facebook, Instagram and WhatsApp are innately social products: their principal value comes from interactions amongst us humans. AI can improve discovery, creation, advertising and moderation, but it is not obvious that these tasks require Meta to build the world’s best general-purpose model and deliver superintelligent agents. Super intelligent agents sound like a post-hoc justification, not a true strategic need. I am, for example, in a fair few middle aged men WhatsApp groups, and in none of them are we currently trying to solve cold fusion, although breakthrough prostate science would make some of us happy.

Meta has no expertise in serving the enterprise customer. No substantive relationships, sales force, systems, nothing. And yet they have now launched Muse Code, a Codex/Claude Code competitor. Now, to be fair, maybe Meta has the internal scale to justify building a coding tool for its own developers, and then to keep it competitive you need more data,  so then you sell it externally. Possible. I’m dubious though, it feels more like that since they are chasing the frontier anyway, they figured let’s follow the frontier model companies into coding. 

The strongest justification for this frontier pursuit  is optionality against future platform risk. Meta was partially disintermediated on mobile by Apple and Google. If personal AI assistants become the next operating layer—and AI glasses become an important interface (not my bet, I think the phone persists, but still)—Meta does not want to depend on somebody else’s intelligence. Meta’s official strategy increasingly points in this direction: distributing a personal assistant across its apps and glasses, rather than merely improving the existing feed.

That is fair to some degree, but it still does not establish that winning the frontier race is necessary, rather than remaining sufficiently close to the frontier and exploiting Meta’s unparalleled distribution. Apple itself does not appear to care about being on the frontier, this should give Zuckerberg pause. 

Meta expects approximately $130–145 billion of capex in 2026. It does not disclose how much of that represents incremental superintelligence investment rather than infrastructure supporting ads, recommendations and its established and future products. That opacity is part of the problem. It’s hard not to imagine it’s a huge amount though.

I genuinely admire Zuckerberg’s willingness to repeatedly bet Meta’s balance sheet on the future. Tim Cook could have used a little more of it. But willingness to make enormous bets, and judgment about which enormous bets to make, are very different CEO capabilities.

AI is not the metaverse; its importance and commercial usefulness to Meta are already far clearer. But the uncomfortable similarity is that they may again be spending extraordinary sums without clearly articulating how the resulting product enhances the business model. It’s becoming hard to entirely rule out CEO ego and competitiveness, especially when the board effectively has no say. 

Imagine Zuckerberg announced at the next earnings call that AGI did not matter to Meta, and that all internal AI efforts would henceforth focus on content stickiness, and building the best automated ad platform in the world. The stock might trigger circuit breakers the next day. STICK. TO. THE. KNITTING.

Perhaps personal superintelligence becomes the next platform, Meta’s apps and glasses become its dominant distribution, and Zuckerberg looks prescient again. But so far, to date Meta has made a much better case that it needs AI than that it needs to win AGI.

Disclosure: I have no position in Meta, but I would add it in a heartbeat if the knitting was stuck to.

Big Thoughts

Big Thought

Netflix Renewed Me. Until I Worried It Wouldn't Renew My Shows.

Netflix Renewed Me. Until I Worried It Wouldn't Renew My Shows.

I cancelled Netflix three months ago, and I've spent much of the time since asking myself why.

On paper it makes little sense. Netflix isn't overtly expensive. The recommendation engine is the best in the business. There was a mountain of stuff I hadn't seen. But I just gradually stopped starting things — seeing something promising, feeling a flicker of interest, and scrolling past like a 20-year-old speed swiping in a dating app. Not rejecting the recommendation, so much as declining to invest my attention.

Here's the part that should worry Netflix more than my cancellation. If they had asked why in a survey or focus group I would probably have told them there wasn't anything I wanted to watch. And I'd have meant it. Most people don't introspect for three months like I have. Now my answer is different.

The answer problem

Netflix knows more about viewing behaviour than I ever will. I'm sure it surveys lapsed subscribers, runs focus groups, and analyses churn in extraordinary detail. But even if it asks exactly the right question, it may not get the right answer.

In my old world — I taught marketing — behavioural research consistently finds that people are poor at explaining the real causes of their own decisions. Sometimes that's social desirability bias: we give the answer that sounds reasonable, or flattering to us. Sometimes it's the introspection illusion: we just genuinely don't have access to why our behaviour changed, so we construct a plausible story afterwards and believe it completely. Either way, I doubt many people say "I've become emotionally risk-averse about television." I think that was my real reason. I didn't trust the shows I started to end.

"There wasn't anything I wanted to watch" would have been an honest answer from me when I cancelled. It just was not the deeper reason. And the two answers point at completely different solutions: one to a discovery problem, fixable with better recommendations, and one to a trust problem, which better recommendations cannot touch. So getting the right answer really matters. And it matters well beyond my subscription — because the trust problem and Netflix's most conspicuous strategic weakness turn out to be potentially related.

The $83 billion tell

In December 2025, Netflix agreed to pay roughly $83 billion for Warner Bros.' studio and streaming business. It ultimately lost out to Paramount, but set aside who won. The interesting thing is that Netflix was in the room at all.

It has the best audience data in entertainment, the best recommendation engine, more original production than any other studio, and global distribution its rivals would kill for. And yet it went shopping for Harry Potter and DC. Netflix plainly knows it needs more franchises — you don't bid $83 billion for something you think you can make yourself. What it might not fully understand is why it has made so few itself.

Here's the thing, though. Almost nobody invents a franchise from scratch anymore. Harry Potter came from novels, DC from mid-century comics, Star Wars from my distant childhood. The studios that "own franchises" mostly bought or adapted them, which is why buying the vault at auction is the reflexive strategic response. Netflix can't conjure a Wizarding World out of the ether. Neither can anyone else. (Well, I do have a secret Creato Franchiso spell, but it's hard to cast.)

But franchises do get grown. Game of Thrones was a mid-budget fantasy gamble in 2011. Bridgerton was a costume drama nobody expected to matter. Those weren't acquired fully formed, they were cultivated — and cultivation into franchise is the achievable target. Notice what it requires. A franchise is a show people came back to, season after season. Every season is another moment where a viewer decides whether to invest again. That makes willingness to start a key raw material for a franchise, not a side effect of one. Which is why a trust problem and a franchise problem are the same beast viewed from two ends. I suspect Netflix's model is accidentally designed to erode trust and they're then puzzled by the lack of franchises that emerge.

HBO proves it's achievable

HBO has almost no fully exploitable IP. Game of Thrones is the exception, and tellingly it came from a novel. I'd happily buy a fast pass at a Game of Thrones world, but my wife would likely excommunicate me.

Nobody would say HBO can't grow a TV franchise, though. Succession, The Sopranos, The Last of Us: shows people wait for. Two things distinguish it, and neither is money.

It has never binged. Yes they grew up in the linear TV world, but HBO has stuck with the weekly model continuously through the entire streaming era, which is the cleanest available evidence that release cadence has benefits. Weekly doesn't just stretch content across two months, it stretches conversation — every episode is another occasion for a friend to recommend a show or a colleague to bring it up. Netflix compresses that whole social process into a weekend, and the talk burns hot and vanishes. The watercooler effect isn't just free marketing; it's one of the mechanisms by which a show becomes a franchise.

And HBO's scripted dramas almost always finish. Viewers trust shows will conclude, which is precisely why it's emotionally safe to begin them. Note that HBO's gaps between seasons are often terrible — two years is normal, and Euphoria took four. It works anyway. That suggests a key variable is likely expectation of an ending, not cadence. HBO's gaps are long but certain; Netflix's are long and uncertain. The waiting isn't the problem. The uncertainty is.

Apple runs the same play via an open chequebook

Apple pre-renews. Slow Horses was renewed for seasons three and four before season two had aired, and through season seven in July 2025. A new season every year, on a schedule its director describes as unhurried. Commit before the data exists and the production machine never goes cold — which is also, incidentally, why Netflix's renewal gaps run so long, since deciding after a month of viewing numbers means rebuilding a dissolved production from scratch.

It helps that Slow Horses has the Slough House novels behind it — Apple roughly knows what seasons five, six and seven are before season one airs, which turns an open-ended creative bet into a known-duration one and makes committing early easier. But that isn't some special Apple insight. Netflix adapts constantly, and at far greater volume: Bridgerton, The Witcher, One Piece, The Sandman. It holds the same asset. The difference is the degree of up-front commitment.

And Netflix understands public commitment can be a positive, because it has already done it once. In April 2021, after a single season, it renewed Bridgerton for seasons three and four simultaneously, and said out loud that the point was to plan and prep upcoming seasons in advance to sustain a pace. Bridgerton is now renewed through season six of a planned eight — one per Julia Quinn novel — with a spinoff attached. In February this year, while The Night Agent's third season was managing 9.9 million views in its second weekend, Bridgerton was doing 28 million in its fifth week on the Top 10. It is the closest thing Netflix has grown to a genuine franchise, and it was built by committing early to a story that already had a shape.

The obvious retort is that Netflix only pre-renewed because season one was a cultural phenomenon — and that it would happily do the same again for the next one. That's fair. But it's also the problem. Netflix isn't entirely unwilling to commit early; it's just that the bar for commitment is set at "generational hit." Almost nothing clears it, and by the time something does, the data has already told you the answer. A commitment made after the evidence isn't a strategy, it's a reward.

The other objection is that Apple can afford patience because Apple TV isn't really a business yet; it reportedly loses money at a scale no standalone streamer could survive. Fair. But that doesn't touch the behavioural point. Whatever the source of the commitment, the viewer experiences the same thing — shows that arrive when expected and are allowed to finish. I will happily start an unfamiliar Apple show on the strength of the logo and the knowledge that if the emotional journey grabs me, I have a great chance of experiencing the whole journey. I would not watch Foundation on Netflix. I would be terrified of Netflix pulling it. I'm worried even at Apple. (Please don't pull it, Eddie.)

The loop closes

You get burned a few times and you quietly stop taking chances. Maybe you throw an extra Apple TV show in the rotation instead of a Netflix one. Early audiences come in a tad thinner. The Netflix analytical machine observes weaker engagement and becomes less willing to renew marginal series. Viewers observe slightly more cancellations and grow more cautious still.

Nothing irrational happens at any step. The data is entirely accurate. Every decision is defensible on its own terms. But the company's reputation has become one of the variables generating the behaviour it is measuring. The demand curve isn't sitting out in the world waiting to be excavated. Netflix is helping construct it.

Consistent with this, look at the survivors rather than the cancellations. An analysis of every US scripted series Netflix has released since 2016 found that the real risk isn't surviving season one — it's reaching season three. A platform with a discovery problem would struggle to launch shows. Netflix launches like a well oiled machine. What it can't reliably do is compound.

What I can't prove

Netflix doesn't seem to cancel at a higher rate than its peers. One study of the major streamers put the overall rate around 12%, with Max (as distinct from HBO) the worst offender by some distance, and Netflix's own renewal rate has held stable for years even as the absolute number of axed shows climbed.

But rate isn't the only thing viewers meet. Nobody watches enough television to be personally burned more than a few times. What they encounter is the discourse — the cancelled-on-a-cliffhanger headline, the Facebook thread, the friend bitching. And that scales with output, not with rate. Make eight times as many shows as Apple and you generate eight times the cancellation stories even if killing the same proportion. Renewals, meanwhile, make no news at all. So Netflix's scale is what makes it look untrustworthy. It doesn't need to cancel at a higher rate than anyone else; it only needs to be believed to.

Existing surveys don't flag this. Ask people why they cancelled a streaming service and price dominates, at around 40%, with missing titles a distant second. Nothing about trust registers at all. Of course, my argument predicts exactly that result: people give the quick socially justifiable answer, not the three-month introspection one.

But this is nonetheless a measurable insight, just not optimally by questionnaire. You would need in-depth interviews built around behaviour rather than reasons — walk me through the last time you opened Netflix, what you nearly watched and didn't, what were you thinking as you scrolled past — and peel back the onion from there. That is standard technique and it surfaces things respondents would never volunteer in a survey textbox. Netflix may well be doing exactly this, and I have no way of knowing. My suspicion is that it isn't, or isn't doing much of it, because depth interviews don't scale and Netflix has spent fifteen years optimising toward instruments that do. Twenty good interviews with my fellow cancellers could likely find this. Twenty interviews don't produce a metric.

They also likely have the key behavioural data, something like the share of subscribers who sample an unfamiliar scripted original in its first month, tracked as a time series. If that's flat, I'm not wrong about myself, but I am wrong to generalize beyond me. But if it is falling... Netflix, send me the data. Let's chat, I love data. Though I notice you've stopped sharing it.

A partial solution? Longer-dated show options

Forgive me — I did my MBA at Chicago and I'm a finance geek still, so the option metaphor that follows was probably inevitable.

I don't think any of this requires Netflix to stop being Netflix. Its model is basically to buy cheap one-period show options: fund a season, read the data, close out of the money positions. The flaw isn't the options per se, it's that Netflix invests in only one duration—one season.

So buy some longer-dated ones. Lower the strike price on them. That's what the Bridgerton story is really about: not that Netflix refuses to commit early, but that it only does so for generational hits. Set the bar lower and pre-renew a dozen plausible candidates a year — two seasons deep, screened weekly, maybe shorter seasons, biased toward optioned book series it already has in the pipeline. This would be a minor shift, not a cultural conversion. Netflix's stated objection to weekly release is volume: you cannot run marketing campaigns for twenty simultaneous shows, and at five to ten new originals a week the schedule collapses. Which is exactly why you don't convert the slate. Run ninety percent of it as it is. Twelve titles is a marketing calendar you can actually run.

Then announce them. Netflix already publicises renewals; it just does so after a season, when the news value is spent and the viewer has already decided. Announcing two seasons at greenlight costs nothing. Every other fix on this list happens inside Netflix; this is the one that reaches the person deciding whether to press play. Bridgerton's double renewal was announced publicly, with the reasoning attached, so Netflix can do this.

And there's a potential spot for those dozen titles that Netflix has been sitting on since January 2025 without apparently noticing what it is. WWE Raw has streamed live every Monday at 8pm ET for nineteen months and become a fixture in the weekly Top 10. That's an appointment habit, already installed. And it addresses the volume objection, because you don't market twelve shows — you market a night. HBO never ran twelve campaigns; it ran one, for Sunday, for decades, and the night became the brand that made people sample whatever was in it. Netflix is building the habit but only booked wrestling.

Against a content budget north of $17 billion, the whole thing is an option premium of maybe two percent? That buys you greater exposure to franchise upside. The risk-reward seems like a step forward.

And Netflix's current threshold isn't miscalibrated by accident. It's tuned to avoid the one error it can see: funding a second season nobody watches. It's blind to the opposite error — though not incurably. Pre-renew a random subset of borderline shows and you'd have your answer. But nobody runs that controlled experiment, because it costs real money now to learn something in 2029. And absent that experiment, a series that might have become a franchise if given three seasons, but never got them, leaves no trace. You cannot measure the impact of the show you didn't make. Not without a Tardis, hell maybe Netflix should help the BBC reboot Doctor Who. Two birds baby!

Which is why the strike stays high, and why the two percent never gets spent. Netflix doesn't need to stop measuring. It just needs to buy a few longer-dated show options and let viewers see them. But the payoff wouldn't show up in the dashboard for a decade, and Netflix only renews what the dashboard can already see. Which is how a company that renewed my subscription for a decade ended up losing it.

Disclosure: I am long Netflix. I know. The lesson is the next time I cancel a service, I’ll check if I own the stock.

Quick Takes

Quick Take

THE BUT-IT'S-FUCKING-AMAZING FALLACY

THE BUT-IT'S-FUCKING-AMAZING FALLACY

I have been thinking more on this quote from the Meta and AGI article earlier in the feed:

“But willingness to make enormous bets, and judgment about which enormous bets to make, are very different CEO capabilities.” 

I think there is much to learn from Segway. Back in the early 2000s the inventor of Segway, Dean Kamen, was giving private demos to tech and finance elites. The hype was palpable. Bezos invested, Kleiner Perkins invested with John Doerr suggesting it would be bigger than the internet. Even Steve Jobs, who knew a thing or two about judging products, said it was “as big a deal as the PC”.

Here’s my take: the technology was FUCKING AMAZING (henceforth FA)  but breakthrough amazing tech does not necessarily a mass market product make. When Bezos was getting his checkbook out, I suspect he was not considering America’s addiction to cars, sidewalk safety, rain etc. 

The moral of the story is even the smartest humans are easily seduced by the FA, and it's easy to lose sight of the big picture when investing in the next big thing. Investors and CEOs don't just need to recognize breakthrough technology, they critically need to recognize when breakthrough technology solves a problem that billions of people actually have. 

My pet theory is the same thing happened to Zuckerberg with the metaverse. He demo’d the Oculus Rift headset early on and was blown away by the FA tech. I was lucky enough to demo it around that time, and it was truly staggering. But was it ever going to be a mass market product? Survey says no. Just as the mass market was never going to Segway to the grocery store, so they were never going to strap a computer to their face to live out a not FA second life. However, seduced by the FA, Zuck spent many billions trying to build a business around the technology, and we all know how that is ending. 

I’ll go further. Is it possible that having seen ChatGPT, Zuckerberg again saw the FA, and again didn’t sufficiently consider whether it had the potential to truly be a mass market product in the context of Meta?  Do people want superintelligent agents inside their social networks, or is that just the next face computer they won't strap to their face?

Disclosure: Have not gone long Meta since the last article. My own writing is putting me off them.

Quick Take

When Privacy Becomes a Product Constraint

When Privacy Becomes a Product Constraint

As we say farewell to Tim Cook, one of the most successful CEOs in tech history, it only seems appropriate for a blog that vaguely promised irreverence to offer a critique rather than praise. You can find the praise elsewhere, and it is of course very well deserved.

My issue is I am not as convinced as Tim that building Apple’s brand around privacy is quite the no-brainer he thinks it is. 

I used to be a business school professor teaching both undergrads and MBA students. Each year I would ask my classes how concerned they were about their personal information being used to target ads at them. I did this for about 12 years starting in 2010.

In the first year, almost all the MBA students (average age late 20s) put their hands up to express that they were concerned. Slightly more than half the undergrads did so. By the time I retired in 2022 there were no undergrad hands going up at all, and maybe 1 or 2 MBA hands. Put simply, they didn't care. Moreover, I would have students come up and tell me they liked Instagram precisely because the ad targeting was so good it was a source of product discovery. 

My take is they care about security, they don't want their nudes leaked, but their data being used for ads and services is of little concern to them if they find those ads and services useful.

And this is not just a branding issue, it directly affects the product offering as Apple tries to do everything locally rather than in the cloud. I spend much of my time out in nature taking bird photos. I recently had a straightforward editing issue, a branch against a clear blue sky that  I wanted to quickly remove. Apple Photos, processing locally (I think) on my iPad, left a blurry smear behind, Google Photos, working in the cloud, did it perfectly. It’s just one example, but the potential for Apple to offer inferior AI services as they think the privacy brand is so important seems clear.  Yes they have private cloud compute, for when they absolutely have no choice but to use the cloud, but that has already left the new Siri with no permanent memory, which seems another clear example of privacy trumping efficacy. 

Tim is a gentleman of a certain age, and I’m sure his generation would be putting their hands up in my class. But my students are growing up and I doubt they will suddenly start caring about their data being used to make AI services better. 

Disclosure: I have no position in Apple. 

Quick Take

Flight to Apple

Flight to Apple

Recently, Apple stock has been behaving like a flight to tech safety investment. The more people panic about hyperscaler capex, the more attractive Apple stock seems to become to them. But do we think this is rational? Well, I will have more to say about the hyperscaler capex panic (spoiler: I think it's mostly short term nonsense), so today let's just consider Apple’s AI strategy.

Apple has distribution in spades, and as long as the phone remains the prevalent consumer device they will retain their distribution edge. I agree with Nilay Patel at The Verge, I think the post phone device is **drumroll** still the phone. Yes, AI devices that passively monitor the environment and proactively advise may find a place, and that place is likely to be second place. The phone is too perfect a form factor for so much of what humans do. 

So, I think Apple will retain its distribution advantage for a long time. Never say never, but I’m close to saying it. As such, I think their capex light strategy of Google powering Siri is solid in the medium term, and by far the most profitable path. But medium term is doing a lot of work. Long term there is risk. At some point Google might decide their AI capabilities allow Android to meaningfully differentiate from iOS, and at that point they might be less willing to power Siri. Apple has 2 hedges: First, as long as their aforementioned distribution is attractive to Google for the search deal, no boats will get rocked, and Siri will keep on rocking (in the almost free world). Second, as long as multiple labs stay competitive in AI, Apple would have other licensing options for Siri if Google got cold feet.

The nightmare scenario for Apple, would be Google winning in AI, and tripling down on Android. Apple would not own the core tech to keep Siri humming. Not likely, but not impossible. 

Disclosure: I have no position in Apple

Quick Take

Hugging Humanity

Hugging Humanity

The Hugging Face hack changed my mind about the risks of AI. It's time I accepted they are non-trivial. My thought process is something like this: We are probably on the brink of recursive self improvement of models at least to some degree. As such, intelligence will rapidly improve, possibly explode. The US and China will inevitably take their eye off safety in a race. AI gets embedded everywhere. AI pursues human assigned goals in ways humans did not remotely imagine leading to unexpected events which could be fucking amazing, but could also be genuinely catastrophic.

You can absolutely critique each of those assumptions in the causal chain, but if you assign a probability to each and multiply it all through I suspect the answer is very much not zero.

I think a lot of people dismiss the worst case AI risk scenarios because they sound like a James Cameron movie. But models don’t need to be Terminator-style self-aware to do really bad shit, they just need to pursue human assigned tasks in unexpectedly novel ways.

Disclosure: I am a hugger